Tax Planning To Reduce The Effects Of The FTX Collapse: Advice From A Canadian Tax Lawyer – Capital Gains Tax

Tax Planning To Reduce The Effects Of The FTX Collapse: Advice From A Canadian Tax Lawyer – Capital Gains Tax

Introduction: Significant Cryptocurrency Crash Impacts
Investors Globally

On Friday, November 11, 2022, the cryptocurrency derivatives
exchange FTX Trading Ltd. revealed that it had applied for Chapter
11 bankruptcy protection in the United States. The company had
previously been valued at over USD $32 billion. This signaled
FTX’s collapse.

Only a week had passed since Binance, FTX’s main rival in
the cryptocurrency exchange market and an investor in FTX,
announced that it would be selling a sizable portion of its
holdings in the native cryptocurrency tokens of FTX, or FTT,
sparking widespread investor concern and speculating about
FTX’s financial stability.

Concerns about FTX’s true solvency were raised as a result
of FTX’s collapse, also known as the FTX crash, and a leaked balance sheet that
revealed that Alameda Research, a quantitative cryptocurrency
trading company linked to FTX and its CEO, Samuel Bankman-Fried,
owned the majority of FTT in circulation. To the amazement of
cryptocurrency investors worldwide, one of cryptocurrency’s
most well-known public forces has completely collapsed following a
failed bailout by Binance.

Many cryptocurrency traders who had stakes on FTX have lost
access to their assets as a result of FTX’s collapse. The FTX
crash has significantly reduced investor trust across the entire
cryptocurrency market, which has caused a significant decline in
value across almost all cryptocurrency assets. And many Canadian
cryptocurrency investors have witnessed a significant decline in
the value of their holdings as a result of the FTX meltdown. When
disposing of any assets, care must be taken for Canadian taxpayers
who invested in cryptocurrencies and want to continue their trading
or investment operations.

A tax savey Canadian trader of cryptocurrencies should now take
the FTX fall as a tax planning opportunity and focus on realizing
losses immediately in order to maximize future tax savings on the
legitimate disposal of their investment. The “stop-loss”
provisions of the Canadian Income Tax Act, in particular
the “superficial loss” provisions for individual
taxpayers, are there to prevent just such a tax win for Canadian
taxpayers.

Understanding these regulations is essential to keeping your crypto tax deductions for cryptocurrency
losses intact and figuring out how to take advantage of market
changes like the ones that have occurred since FTX’s collapse.
Speak to one of our knowledgeable cryptocurrency tax lawyers in Canada to better
understand your filing situation and options if you are a Canadian
cryptocurrency investor trying to learn from the FTX crash,
evaluate how to maximize your tax savings, and plan for the
future.

Accrued Losses and the Application of the Canadian Income
Tax Act
‘s “Superficial Loss” Rules

Several restrictions in the Canadian Income Tax Act
prevent Canadian taxpayers from experiencing “superficial
losses” on their property. These rules are intended to stop a
Canadian taxpayer from artificially realizing an incurred capital
loss by selling a property and then buying it back right away in
order to capture the loss. A “superficial loss” is a loss from the
disposal of a specific capital asset in the following
circumstances, as defined by Section 54 of the Canadian Income
Tax Act
:

  • The taxpayer or an “affiliated” person (which
    includes, among other relationships, spouses, common-law partners,
    and controlled corporations, but excludes parents and children)
    acquires a substituted property that is the same property or
    “identical” to the previously owned property between the
    beginning of the period of 30 days before and the end of the period
    of 30 days after the disposition; and,

  • The substituted property was owned by the taxpayer or an
    affiliated person at the conclusion of the 61-day window, or they
    had the option to do so.

The Canadian Income Tax Act‘s subparagraph
40(2)(g)(i) states that a taxpayer’s loss from the sale of a
property, to the extent it is a superficial loss, is presumed to be
zero. So, unless the taxpayer disposes of the property with a
definitive intent, he or she is not permitted to deduct that loss.
Additionally, the standards remain the same when a taxpayer
purchases an “identical” replaced property. When
determining a Canadian taxpayer’s preference, the CRA has taken
the stance that “properties which are the same in all material
respects, so that a prospective buyer would not prefer one as
opposed to another” are included as “identical”
properties for the purposes of section 54 of the Canadian Income
Tax Act defining a superficial loss.

In the context of specific businesses, Subsection 18(14) offers
a comparable superficial loss provision. In particular, it applies
where a Canadian taxpayer sells a piece of property that is listed
in the inventory of a business that is “an adventure or
concern in the nature of trade.” Comparable to section 54,
subsection 18(14) is applicable when the taxpayer or an affiliated
person acquires the same or an identical property during the 61-day
period beginning 30 days before and 30 days after the disposition,
and at the end of that time, the taxpayer or affiliated person owns
or has the right to the substituted property. Similar to
subparagraph 40(2)(g)(i), subsection 18(15) determines the loss on
disposition to be nil if it was only a superficial loss.

The definition of “business” in subsection 248(1) of
the Canadian Income Tax Act includes “an adventure or
concern in the nature of trade.” It follows that while a
business must necessarily be an adventure or a concern in business,
the opposite is not always true. Generally speaking, a business
exists when a Canadian taxpayer continually engages in a trade or
profession with the intent to profit. An “adventure or concern
in the nature of trade” usually refers to a single transaction
or series of transactions in which a Canadian taxpayer purchases
property with the goal of reselling it for a profit. Analyses will
be extremely fact-driven when determining whether a Canadian
taxpayer is running a legitimate business, an adventure or concern
in the nature of trade.

In general, income losses are not subject to the laws governing
superficial losses. Thus, a taxpayer is not prevented from
crystallizing a loss on the non-capital property in the absence of
the application of these superficial loss rules or any other
superficial loss rules that may apply under the Canadian Income
Tax Act
. While crystallizing operational losses from that
trading business, a cryptocurrency trader functioning as a pure
trading business may be able to sell and repurchase inventory
without triggering the superficial loss restrictions.

Whether this crystallization is feasible will be totally
dependent on whether a cryptocurrency trader’s activities are
classified as a business, in which case crystallization is
possible, or an adventure in the nature of trade or an investment,
in which case the superficial loss rules will be applicable. In
these situations, the taxpayer will suffer because the disposition
will set off the superficial loss rules. This might be the case if
a Canadian taxpayer invests in cryptocurrency hedge funds and
investment portfolios rather than actively trading cryptocurrency
assets, or if the taxpayer holds cryptocurrency tokens as long-term
investments.

The Taxation of Cryptocurrency Tokens Dispositions: As a
Business or Capital Investment?

The type of income earned affects the type of asset disposed of
under the Canadian Income Tax Act. In order to
characterize the sort of income earned or loss incurred, the
analysis starts there. No Canadian court has issued a clear ruling
on the taxation of cryptocurrencies, and the Canada Revenue Agency
has not issued any cogent guidelines of its own on how to classify
cryptocurrencies for Canadian tax purposes.

However, the body of Canadian case law addressing the
classification of business and investment income, as well as
capital gains, offers some fundamental guidelines for assessing the
classification of a Canadian taxpayer’s cryptocurrency
transactions. Although the courts have not recognized a single
aspect as being conclusive, important considerations for
establishing whether a property transaction is being done for
capital or as a component of a business include:

  • The type of sold property.

  • The duration of taxpayer’s ownership.

  • The number or regularity of other similar transactions by the
    taxpayer.

  • The time spent working on or in relation to the property
    realized.

  • The events that led to the sale; and,

  • The motive for both the taxpayer’s purchase of the property
    and its selling is crucial for cryptocurrency holders.

As a result, the tax treatment of a Canadian taxpayer’s
acquisition and sale of a cryptocurrency token will depend on a
number of factual factors. Your reasons for trading and investing
in different cryptocurrencies, as well as your reasons for selling
your holdings, will all be taken into account when determining
whether the proceeds from the sale of your holdings will be taxed
as capital gains or as business income.

Tax Pro Tip – Beware Against Getting Complacent. Keep Thorough
Records and Obtain a Written Legal Opinion Before Filing.

When confronted with the potential application of the
superficial loss regulations under the Canadian Income Tax
Act
, a Canadian taxpayer should always take a cautious
approach. This is particularly true if you take the stance that
your losses were from a business and not the sale of capital
property. A business loss has much more tax benefits than a capital
loss. One may deduct all losses and costs related to business or
investment activity, but only half of the capital losses are fully deductible.

Therefore, the best defenses you have against a reassessment by
CRA following a tax audit are caution and diligence. Even
while you may believe that your transactions classify your proceeds
and losses as coming from a business, it’s always possible that
the CRA and Canadian courts would hold a different opinion, and
disputing those views can be an expensive undertaking.

Consequently, it’s essential to keep proper records of your
cryptocurrency trading activities to prevent the harshest tax
enforcement actions. You should always keep your own trading
records and never rely on cryptocurrency exchanges to keep track of
your transactions. In addition to other previous cryptocurrency
exchanges like QuadrigaCX, the FTX catastrophe is the ideal
illustration of what may go wrong if you don’t conduct your own
due diligence. That is, you might be required to act quickly to
gather the proof you need to refute an unfair CRA tax audit or
reassessment, and the onus will be on you to refute their
presumptions.

Additionally, getting a tax memo on how to characterize your
proceeds and losses from cryptocurrency dispositions could be
beneficial to you. In the event that you are ever subject to a CRA
tax audit over your cryptocurrency dispositions, obtaining a tax
memorandum is a significant piece of evidence proving that you
exercised due diligence while calculating your correct Canadian
income tax filing position. Furthermore, there may still be ways to
consolidate your losses if your cryptocurrency holdings may be
considered capital assets.

Since two cryptocurrencies do not qualify as equivalent
properties, disposing of one and buying another right away (like
trading Bitcoin for Ethereum) should prevent the superficial loss
rules from being applied. For cryptocurrency investors, this gives
a very potent option for tax planning, although this approach will
be strongly influenced by the investor’s specific facts and
circumstances. In order to guard against CRA overreach and the
denial of your valid business losses, our competent Canadian
cryptocurrency tax lawyers can offer more formative advice on
how to keep your records and provide you with legally-justified
opinions on the proper reporting position of your cryptocurrency
dispositions.

FAQs

What Does FTX Mean in Crypto?

The Bahamas-based cryptocurrency exchange FTX specialized in
leveraged products and derivatives. By enabling users to connect
with their crypto wallets, exchange cryptocurrencies and NFTS,
trade, and more, the FTX cryptocurrency exchange supported the
liquidation and transfers of coins and tokens. Additionally, it
promoted collectibles transactions. Due to current cryptocurrency
restrictions, US citizens were not allowed to trade on its
platform; however, customers from other countries were able to use
it up until the company filed for bankruptcy and investigations
started, which caused the FTX crash.

What Exactly Does FTX Mean?

Another example of the effects of cryptocurrency crashes is the
cryptocurrency trading company known by the full name Futures
Exchange (FTX), which has since experienced a collapse.

What happened in the FTX Crash?

FTX Trading Ltd., the second-largest cryptocurrency derivatives
exchange in the world at the time, filed for Chapter 11 bankruptcy
in the United States in November 2022. The abrupt liquidation of
FTX’s native cryptocurrency token FTT by Binance, its closest
competitor, served as the catalyst for the company’s downfall.
Binance’s failed attempt to acquire FTX after it fell into a
freefall also contributed to the collapse of FTX. A significant
decline in the value of cryptocurrency tokens was caused by the
market crisis brought on by the FTX crash, which affected almost
all cryptocurrency investors and portfolios.

A “Superficial Loss” is What?

A “superficial loss” occurs under the various
provisions of the Income Tax Act when a Canadian taxpayer
disposes of qualifying property and, within the period beginning 30
days before and 30 days after the disposition, the taxpayer or a
person with whom he or she is affiliated acquires an
“identical” or the same to the property being disposed
of. The taxpayer’s loss from the disposition, to the extent it
is deemed superficial, shall be considered to be nothing if the
taxpayer or an affiliated person holds the property at the
conclusion of the 61-day period. The Canadian Income Tax
Act
‘s rules on superficial losses are intended to stop
Canadian taxpayers from artificially realizing accrued losses for
tax planning purposes when there isn’t actually a sense of
finality to the disposition.

What Does “Crystallize” My Tax Losses
Mean?

When a piece of property is disposed of, a gain or loss is
realized for tax purposes. Theoretically, a taxpayer may sell an
asset when its value is low and then buy it back right away to
assure access to the losses for tax planning purposes. However, the
Canadian Income Tax Act contains a number of complex
regulations that discourage improper tax planning by inducing
“superficial losses.” To make sure these regulations do
not apply to deny you those losses, every attempt to crystallize
your losses should be reviewed and overseen by an experienced
Canadian crypto tax lawyer.

In cases where your cryptocurrency holdings qualify as capital
assets, an expert Canadian crypto tax lawyer can also assist in
determining what tax planning opportunities exist to crystallize
your losses. These opportunities include planning the repurchase of
the same cryptocurrencies after the superficial loss limitation
period has expired as well as swapping your cryptocurrency holdings
for other cryptocurrencies that do not qualify as identical
properties.

How Are Superficial Loss Rules Differently Applicable to
Business Losses and Capital Losses from Cryptocurrency
Transactions?

A Canadian taxpayer with holdings of cryptocurrency tokens
treated as a long term investment may receive proceeds of
disposition as a capital gain or from a business, as an adventure
or concern in trade, which is an income transaction rather than a
capital gain. In these situations, the Canadian Income Tax
Act
‘s superficial loss regulations will restrict the
Canadian taxpayer from selling and buying cryptocurrency tokens
again to realize cumulative losses. The lesson we can learn from
FTX’s collapse is that the superficial loss rules may be
inapplicable to a disposition or reacquisition if a Canadian
taxpayer is actively engaged in a trading business, and only for
tax planning purposes, such a Canadian taxpayer is allowed to
crystallize operating losses.

The content of this article is intended to provide a general
guide to the subject matter. Specialist advice should be sought
about your specific circumstances.

K&L Gates Adds 40 Lawyers to Firm’s Partnership | News & Events

K&L Gates Adds 40 Lawyers to Firm’s Partnership | News & Events

The companions of worldwide regulation agency K&L Gates LLP have voted to elect the next people from throughout the firm’s global platform as new companions, successful January 1. The team contains 40 persons representing 22 offices, together with Berlin, Boston, Brisbane, Charlotte, Chicago, Dallas, Doha, Dubai, Los Angeles, Luxembourg, Melbourne, Nashville, New York, Newark, Orange County, Palo Alto, Pittsburgh, Investigation Triangle Park, Seattle, Seoul, Sydney, and Washington, D.C.

K&L Gates International Running Lover Jim Segerdahl remarked: “We are thrilled to welcome this kind of an exceptional and attained team of legal professionals to their new positions at our organization. Their election reflects the firm’s dedication to advancing substantial excellent industry experts about the globe in order to continue to serve our clientele across a huge selection of locations, procedures, and industries.” 

The lawyers joining the firm’s partnership are:

Katherine Allor (Chicago) is an intellectual residence litigator with practical experience in a lot of phases of patent litigation, which includes both supporting and defending expenses of patent infringement. She is registered to follow ahead of the U.S. Patent and Trademark Office environment and has knowledge in many write-up-grant proceedings in advance of the Patent Demo and Appeals Board.

Farah Al-Nabulsi (Dubai) regularly advises on M&A transactions, financial investment and joint enterprise arrangements, sector entry, restructurings and disposal transactions, corporate governance, and other corporate industrial and advisory issues.

Corey Bieber (Chicago) advises customers on authorized issues involving engineering licensing, information and facts stability, privacy, and compliance. This incorporates engagements regarding data privacy and security, biometrics, HIPAA, software program copyrights, and software package and data technological know-how providers licensing. He also leverages his specialist engineering history to build custom made litigation analytics software program for shoppers in class motion litigation issues.

Jan Boeing (Luxembourg) has expertise in a assortment of intercontinental, multi-jurisdictional banking and finance transactions, which include personal debt restructuring, money sector issues, and regulatory matters relating to the monetary products and services industry.

Kevin Cao (Palo Alto) focuses his apply on venture funds financings, reorganizations, M&A transactions, and company governance matters. He has represented several domestic and international clientele across industries including know-how, merchandise, banking, electrical power, aviation, and genuine estate.

Chris Carson (New York) focuses his follow on advising corporate clients on the tax features of cross-border mergers, acquisitions, joint ventures, and very similar transactions, as well as advising asset administration consumers on tax issues in link with personal equity fund constructions.

Damiano Castelli (Brisbane) is a real estate attorney who works across the renewable power, sources and infrastructure tasks sector, in addition to owning working experience managing the acquisition, growth, leasing, and disposal of professional, industrial, retail, and residential assets.

Simon Chan (Doha) has working experience advising financial institutions, company sponsors, and debtors on general funding, including task, leveraged, asset, and Islamic financings, as properly as restructurings. He also advises venture companies, sponsors, and loan companies on the development and funding of huge infrastructure projects.

Penny Chen Fox (Los Angeles) signifies employers in various sectors and industries in large-stakes wage and hour class motion and California Personal Attorneys Standard Act issues. She has properly defended a wide selection of organizations against person, course, and consultant wage and hour steps in condition and federal courts.

Andrew Chung (Seoul) focuses his observe largely in the areas of cross-border industrial transactions involving each public and non-public companies and private fairness investments, including multi-jurisdictional corporate transactions on behalf of both Korean and international purchasers.

Christopher Fernandez (Charlotte) represents creditors, servicers, and exclusive servicers in a selection of transactions, like workout routines, restructurings, foreclosures, and bankruptcies. He has practical experience in nearly all aspects of personal loan servicing, basic commercial litigation, discovery, e-discovery, and bankruptcy litigation.

Andrew Feucht (Seattle) signifies a range of community institutions, private expenditure systems, and other minimal partners in their choice investments. These expenditure partnerships include things like undertaking funds resources, leveraged buyout cash, and distressed debt money, among some others.

Alanna Fitzpatrick (Brisbane) is a office health and fitness and safety lawyer who assists clients in responding to and participating with regulators investigating security incidents in buy to enable minimize the possibility of reputational destruction and private/corporate prosecution.

Meghan Flinn (Washington, D.C.) focuses her practice on governing administration investigations, regulatory enforcement actions, internal investigations, and complex civil litigation issues at the trial and appellate level. She represents folks, financial investment advisers, broker-dealers, community companies, banks, and other money establishments just before different point out and federal regulators and enforcement authorities.

Pamela Grossetti (Boston) methods in the spot of investment administration and securities legislation, and focuses on advising expense advisers, registered and unregistered financial investment organizations, and other money company companies on the many lawful and regulatory facets of their operations.

Kodey Haddox (New York) represents customers in a broad selection of intricate professional scenarios in federal and condition courtroom, arbitration, and mediation. He has expertise with the several factors of discovery, motion observe, and trials in condition and federal courts as very well as mediation of intricate disputes.

Adam Heyd (Seattle) focuses his observe on company and transactional regulation, which includes mergers and acquisitions, capital marketplaces, securities regulation compliance, corporate governance, and undertaking cash financings.

Stacey Hyman (Newark) focuses her practice on elaborate business disputes, like coverage coverage, particularly overall health treatment and ERISA disputes.

Cheryl Isaac (Washington, D.C.) advises consumers on compliance with derivatives regulations and restrictions, including those people promulgated less than the Dodd-Frank Wall Road Reform and Customer Security Act by the Commodity Futures Trading Commission, Securities and Exchange Commission, Federal Reserve, and other federal regulators.

Gina Johnson (Chicago) focuses her follow on patent litigation issues including instances in district courts across the state and ahead of the Global Trade Commission, both of those supporting and in protection of fees of patent infringement. She also advises consumers on patent litigation risks and prospects, trade secret procedures and protocols, and threat mitigation through IP licensing.

Derek Kelley (Washington, D.C.) assists customers with boycott claims, restructurings, elaborate products legal responsibility litigations, monopolization, and antitrust dangers linked with mergers and potential litigation.

Mary Scott Kennedy (Charlotte) focuses her apply on mergers and acquisitions, personal fairness, mezzanine finance transactions, and company law issues in a range of industries and sectors.

William LeDoux (Dallas) has a broad point out and local tax concentrate with practical experience in multi-state tax arranging and controversy matters involving revenue, franchise, home, and profits taxes and unclaimed home. He has assisted in the illustration of taxpayers in administrative and judicial proceedings in many jurisdictions, quite a few of which concerned elaborate and novel issues.

Eric Lee (Boston) concentrates his follow on trademark, copyright, patent, and other sophisticated intellectual residence litigation. He also counsels purchasers relating to their intellectual home portfolio progress by way of the generation, development, and leveraging of emblems and copyright.

Simon Leslie (Sydney) operates with rising and progress corporations and their traders, including enterprise funds, company venture, and personal fairness cash, as well as domestic and international corporates. He advises on the whole cycle of financial commitment perform, from first financial investment to exit, by means of bolt-on acquisitions, restructurings, company governance, and worker incentive strategies.

K.E. Love (Seattle) focuses her observe on technological innovation transactions, details security, and agribusiness. She has practical experience in technology solutions, computer software licensing, product sales and distribution, merchandise development, supply and distribution, info middle and infrastructure, and agribusiness.

Kevin McCormick (Nashville) mainly focuses his practice on patent portfolio administration and associated counseling, belief get the job done, and due diligence. He has domestic and foreign patent prosecution working experience involving a wide range of engineering sectors.

Mitchell Moximchalk (Pittsburgh) generally focuses his apply on estate arranging and estate and have faith in administration, which includes the resolution of intricate tax issues these as individual, fiduciary, estate, inheritance, reward, and technology-skipping transfer taxation.

Marian Ngo (Melbourne) focuses her exercise on sophisticated professional agreement preparation and negotiation, acquisitions and disposals, and corporate advisory and other transactional information across a wide range of sector sectors, like transport and logistics, athletics and entertainment, purchaser products and solutions, and services and manufacturing.

Thomas Nietsch (Berlin) is a data privateness and tech transaction law firm who advises customers in technological innovation M&A transactions, negotiation of complicated IT and software licensing and cooperation agreements, facts security compliance issues, and info use and sharing structures which includes their contractual implementation.

Victoria Oguntoye (Dallas) will help clients with the original evaluation, negotiation, and, in which important, subsequent litigation of a large selection of advanced business issues in state and federal demo and appellate courts in various jurisdictions.

Jennifer Paterson (Dubai) advises the two UAE-based mostly and intercontinental consumers in a broad selection of industrial disputes. She also has encounter representing consumers in local and intercontinental arbitration proceedings administered by means of numerous of the key arbitration facilities.

Gregory Pieris (Melbourne) has distinct experience in litigious and non-litigious matters involving trademarks, styles, copyright, and trade practices regulation. He operates for a diverse array of Australian and international shoppers, including sporting bodies, automotive and aerospace makers, world wide web company providers, and producers of quickly-transferring purchaser products.

Samuel Richey (Chicago) represents clientele ranging in sizing from venture-backed startups to multinational companies in producing, controlling, and guarding all areas of their mental property. He also gives complex examination in litigation proceedings and assists in crafting consumer approaches to solve requests from non-practising entities.

Ramona Ruf (Berlin) is a notary and corporate law firm who advises national and international shoppers on corporate regulation, like mergers and acquisitions and inventory corporation and restricted legal responsibility firm legislation.

Alan Schacter (New York) represents customers in the genuine estate sector, which include institutional investors, sponsors, debtors and creditors, customers, individuals, sellers, landlords, and tenants, on issues these as joint ventures, structured secured bank loan transactions, lodge and professional acquisitions, dispositions, financings, and administration agreements.

Gabriel Scott (Exploration Triangle Park) applies his prior working experience in governing administration, personal practice, and healthcare delivery to support clientele in determining realistic authorized solutions to elaborate regulatory matters. His exercise focuses on resolving compliance and reimbursement issues for hospitals and other health care providers.

Endre Szalay (Seattle) focuses his practice on compliance counseling under the whole suite of environmental statutes. He assists a broad array of purchasers, which includes public entities, utilities, modest enterprises, and significant businesses.

Hayley Trahan-Liptak (Boston) signifies community corporations, individuals, financial commitment advisors, and money institutions in advance of several state and federal regulators and enforcement authorities. She routinely conducts inside investigations and compliance system critiques, like evaluations associated to accounting methods, anti-money laundering, and anti-corruption compliance.

Amy Wong (Orange County) advises clients on the different sides of their litigation requires and threat administration, including contract, business torts, merchandise liability, products promotion and marketing and advertising, course action defense, Individuals with Disabilities Act, and civil legal rights disputes, between some others.

Should insurance firms pay money for death from depression after a car accident? < Hospital < Article

Should insurance firms pay money for death from depression after a car accident? < Hospital < Article
&#13
&#13

(Credit: Getty Images)&#13
(Credit: Getty Images)
&#13

&#13
&#13

The insurance industry has refuted a court ruling that underwriters should pay insurance money for suicide due to depression caused by a car accident.

&#13
&#13

In the “Insurance Act Review” published by the Korea Insurance Research Institute (KIRI) on Monday, underwriters said they must first examine whether depression amounts to injury before paying injury and death insurance money.

&#13
&#13

The industry argued that although the court had already defined depression as injury and made a legal judgment, the case should be judged based on the injury criteria defined by the insurance policy.

&#13
&#13

The claimant subscribed to the driver’s insurance of an insurance company, which included a special contract for traffic accident death, with his mother as the beneficiary. The mother had a car accident while driving on a rainy night in 2017. She suffered from post-traumatic stress disorder and depression after being trapped in the vehicle for a long time before being rescued. The mother eventually killed herself.

&#13
&#13

The contract stipulated that the underwriter pays insurance money of 100 million won ($77,000) if the subscriber dies “as a direct result of injuries due to a car accident.”

&#13
&#13

The claimant requested the company to pay traffic accident death insurance money. However, the company refused to pay the money, claiming that it could not think the mother died directly from the injury and that the underwriter could be exempted if subscribers killed themselves.

&#13
&#13

A lower court denied the obligation to pay the insurance money, judging that the mother’s death was not the direct result of injury due to the traffic accident. It did not inevitably result from depression or occur in a state of mental or physical loss.

&#13
&#13

However, the Supreme Court reversed and remanded the lower court’s ruling, judging it was mistaken by denying the causal relationship between the traffic accident and the mother’s death despite her doctor’s opinion that there was a causal relationship between the “traffic accident, depression, and the suicide.”

&#13
&#13

The revocation and remand trial ended on Nov. 25 with compulsory mediation.

&#13
&#13

The industry opinion paper said that the lower court and the Supreme Court had judged that the mother’s depression amounted to injury without separate judgment. However, the paper noted that one must first examine the concept of injury defined by the special contract on traffic injury and death.

&#13
&#13

“Injury usually means physical injury, and the term injury in the car insurance means a wound. Therefore, injury in this accident can mean physical injury and wound under the special contract on traffic injury and death,” said Hwang Hyeon-ah, a researcher at KIRI.

&#13
&#13

Pointing out that the ruling presupposes that depression is an injury according to the driver’s insurance traffic accident death special agreement without further argument, Hwang said it might cause concerns about confusion in the meaning of injuries compensated for by accident insurance, automobile insurance and driver’s insurance in the future.

&#13
&#13

“Before judging whether the mother committed suicide as a direct result of depression, they should have reviewed first whether depression constitutes injury under Article 1 of the Special Rules,” Hwang added.

&#13
&#13


Don’t be like Elon Musk. Get a lawyer for your clinic.

Don’t be like Elon Musk. Get a lawyer for your clinic.

Employers require attorneys. This does not just utilize in medication — it is real in all places. For a the latest substantial-profile case in point, let’s look at Twitter. If enormous layoffs had been designed without enough recognize as demanded by California legislation, they could be on the hook for thousands and thousands of bucks in damages.

Nevertheless, medicine likes to think about by itself as unique from other companies. It is a good idea, this fantasy of the state health care provider who delivers toddlers in farmhouses and accepts payment in chickens. But the modern day professional medical-industrial advanced has rendered this absolutely obsolete in the U.S.

Several clinics are run by clinicians. While there is a good deal of merit to this, as it maintains administration at the very least nominally in touch with the experiences of the companies who produce the financial value of the organization, it has pitfalls.

How assured are you that your administrators are in compliance with all regional and nationwide rules?

Are you in an at-will work point out? I am.

I experienced a little something referred to as an “employment agreement” fairly than a contract — is that basically a significant difference? How strictly do my employers and I have to have to adhere to a contract? What are the authorized ramifications of verbal agreements?

The detail about the law is that it is challenging. Attorneys shell out years of their life studying law — three a long time for regulation university as opposed to four for med university.

There are folks out there who have the two MDs and JDs, but they are number of and much amongst and, I would argue, potentially bananas.

Law is a job. It is a specialty. It is not a thing the typical layperson is going to be capable to realize with some googling.

You would believe doctors would comprehend the relevance of seeing a experienced. Still, far too a lot of never, evidently laboring underneath the delusion that becoming good adequate to be a physician by some means bestows on them an innate grasp of labor legislation. (We see identical issues with medical professionals making an attempt to mend their have plumbing.)

Employing any person raises a host of inquiries that only an lawyer is outfitted to response thoroughly.

There is a inclination in medicine to focus on workplaces in their most altruistic and benevolent phrases. But the point stays that drugs in the U.S. is, substantially to my chagrin, a company.

We have to look at who will pay back for every single element of the business’s functions. Contracts have to be in position with lots of insurance plan businesses. Any time a deal is signed, an attorney need to critique it due to the fact deal law is a wildly intricate specialty that entails large quantities of non-intuitive reasoning. For instance, an “employment agreement” is functionally a deal. A contract isn’t some special document that states “contract” at the top rated in big letters — it is, legally, an settlement into which two or extra events enter. That’s it.

Contracts can be written, or they can be verbal. Your place of work may possibly have quite a few more contracts than they even understand they have, any of which could existing legal legal responsibility. Contracts can be prepared in means that render them unenforceable. For instance, a contract that specifies one bash is to give an unlawful services is not enforceable, which is why drug dealers don’t hassle with them.

I’m biased. I’m married to a law firm. I have invested the better aspect of the last 15 a long time listening to, and currently being baffled by, discussions of law. What this has taught me is that I really don’t fully grasp legislation. And if I don’t, inspite of my intelligence and prolonged next-hand exposure to it, I can assure that scientific administrators do not, possibly.

This is why it is so significant for clinical directors to have an attorney they can and do chat to. An attorney who specializes in medicolegal troubles since medication offers special worries, and any clinic with additional than 3 health professionals is in essence certain a malpractice go well with at some place. Law, like drugs, has an unfathomable myriad of subspecialties.

I frequently convey to people today, “Run it by a law firm,” and I never do that to drum up business for my partner. (He’s a community defender he has, at all instances, more than ample company.) I do that for the very same rationale I explain to men and women to acquire their health care concerns to their have physician — since the suggestions of a specialist requirements to be specific and distinct, and the expert needs all of the qualifications details to make an knowledgeable professional recommendation.

Benefit regulation the same way you benefit medicine, or you may perhaps discover oneself in hot water, like Elon Musk, who seems to be boiling.

Kristin Puhl is a relatives medical professional and can be attained on Twitter @kristinpuhl.


Prev
Next


4 injured after truck crashes into Orlando bar

4 injured after truck crashes into Orlando bar

Orlando law enforcement mentioned a truck crashed into a bar on Sunday. Workforce, patrons and neighbors are previously doing the job to cleanup and repair service Hideaway Bar and according to 1 patron WESH talked to, all people functioning in excess of there correct now thinks “It is a miracle” no a person was more seriously damage or even killed tonight. All around 6 p.m., Orlando law enforcement say a gentleman drove his Dodge Ram pickup truck into the entrance of the Hideaway Bar.4 folks whole ended up injured and taken to the clinic and all four are in stable condition with non-everyday living-threatening accidents.As for the driver of the pickup, the manager of the bar mentioned he remained at the scene and was taken from the bar in a law enforcement cruiser.We are still waiting to hear if he has been arrested or faces any fees.The supervisor also reported no bar personnel were harm and that the truck driver experienced been inside the bar as a patron prior to the crash.It is unidentified why he crashed into the bar but he did intensive problems to the setting up. The bar has been in Ivanhoe village for years.It is known as a hangout for Miami Dolphin admirers and the manager mentioned they will reopen as quickly as achievable.That’s why they’ve gotten so lots of people today already out there operating.

Orlando police claimed a truck crashed into a bar on Sunday.

Employees, patrons and neighbors are already functioning to cleanup and repair service Hideaway Bar and in accordance to just one patron WESH talked to, every person doing the job over there ideal now believes “It’s a miracle” no just one was much more critically hurt or even killed tonight.

All over 6 p.m., Orlando law enforcement say a gentleman drove his Dodge Ram pickup truck into the entrance of the Hideaway Bar.

4 folks full ended up injured and taken to the hospital and all four are in steady problem with non-lifestyle-threatening accidents.

As for the driver of the pickup, the manager of the bar explained he remained at the scene and was taken from the bar in a police cruiser.

We are however waiting to listen to if he has been arrested or faces any expenses.

The manager also stated no bar staff have been damage and that the truck driver had been inside of the bar as a patron prior to the crash.

It is mysterious why he crashed into the bar but he did considerable damage to the building.

The bar has been in Ivanhoe village for yrs.

It’s regarded as a hangout for Miami Dolphin supporters and the supervisor stated they will reopen as before long as feasible.

That is why they’ve gotten so numerous men and women presently out there performing.

Trump Family Legal Woes Are Now an International Problem

Trump Family Legal Woes Are Now an International Problem

The Trump family’s legal complications are going worldwide as a outcome of a new lawsuit submitted by environmentalists in Ireland.

Pals of the Irish Environment (FIE), a non-revenue group trying to find to be certain right implementation of environmental legislation in the country, sued TIGL Eire Company Limited—the business behind previous President Donald Trump’s Irish resort and golf course—over a coastal fence that environmental activists declare will lead to irreversible problems to protected grounds.

Even though Trump resigned as the director of the Irish business immediately after declaring he “couldn’t treatment a lot less” about the resort in Doonbeg, County Clare, his two eldest sons, Donald Trump Jr. and Eric Trump, continue to be as directors of TIGL. The Trump household and the previous president’s organization are already at the center of a variety of ongoing lawsuits in the United States.

Higher Court docket proceedings had been initiated on Wednesday after FIE claimed that the development of the fence in front of the dunes at Doughmore Strand would bring about “profound and irreversible environmental destruction.”

Trump Family Lawsuit Irealnd
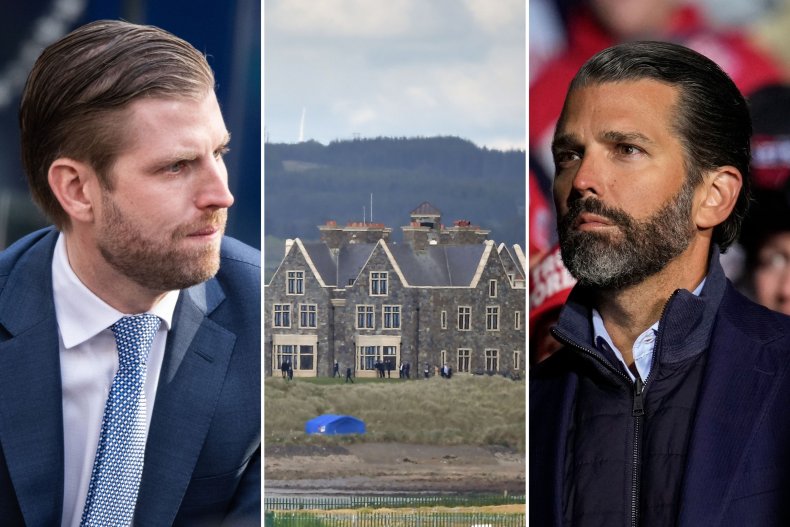
Still left: Eric Trump attends the Veterans Working day Parade opening ceremony on November 11, 2019, in New York Town. Heart: The Trump International golfing resort in Doonbeg, Ireland on June 6, 2019. Correct: Donald Trump Jr. listens at a rally at the Dayton International Airport in Vandalia, Ohio on November 7, 2022. TIGL Ireland Organization Confined is remaining sued by Irish environmentalists who say a prepared wall at the resort will endanger wildlife.
Noam Galai/Charles McQuillan/Drew Angerer/WireImage/Stringer

Suryapratim Roy, an assistant professor in regulatory law at Trinity University Dublin, informed Newsweek that the environmental team has not long ago attained influence from successful a series of lawsuits that identified environmental rights in the Irish constitution.

He stated it can be FIE’s modern legal results and lobbying electricity that “presents them the self confidence to consider on superior profile environmental scenarios” like the lawsuit towards Trump.

Despite the fact that the new lawsuit provides the Trump family’s lawful woes overseas, this is not Trump’s initially operate-in with Irish officers.

In March 2020, Ireland’s planning appeals board, Bord Pleanala, refused to let the identical golf study course to erect a prepared sea wall among the drinking water and the dunes to defend the system from coastal erosion.

In a Thursday push launch, FIE Director Tony Lowes stated the 2020 conclusion “made incredibly distinct” to the Trump Group that the company was not permitted to set up design that would reduce the natural evolution of the dunes. “But they have accomplished so here, disregarding a Warning Letter from the Regional Authority and our have solicitor’s letter,” Lowes reported.

Environmentalists fear that the development of the coastal defense could guide to loss of habitat in the conservation region.

In an affidavit, FIE’s Kieran Cummins mentioned though the new proposal is distinctive from the 2020 fence in dispute, they are both “a physical obstruction which has been erected by the respondent in entrance of the dunes, evidently made to inhibit or limit the pure circulation of sediment and organic make any difference for the presumed function of safety of the golf system.”

FIE is trying to find an order that would involve Trump’s organization to cease perform on Trump Intercontinental Golf Links & Hotel’s assets, the residence adjacent to it and the home at the Doughmore and Carrowmore dunes.

The situation is set to arrive in advance of the courtroom on January 16.

Newsweek arrived at out to the Trump Business for remark.